The Evolution of Elder Fraud: Why Traditional Warning Signs No Longer Protect Older Adults from AI-Driven Scams

The traditional guardrails designed to protect vulnerable populations from financial fraud have fundamentally collapsed. For decades, caregivers, financial institutions, and consumer protection agencies instructed older adults to look for predictable red flags: glaring grammatical errors, unfamiliar international dialing codes, or prize notifications that sounded too good to be true. Today, those rudimentary heuristics are entirely obsolete. The convergence of generative artificial intelligence, sophisticated voice-cloning technologies, and comprehensive data broker ecosystems has transformed online fraud from a game of clumsy phishing attempts into a highly industrialized, hyper-personalized criminal enterprise.
This transformation has placed aging adults squarely in the crosshairs of cybercriminals. Caregivers across the United States are increasingly finding themselves on the front lines of a crisis they were never trained to navigate, often discovering breaches only after significant retirement savings have vanished. Understanding the mechanics of this shift requires examining how modern fraud operates, why older demographics bear the heaviest burden, and why passive warnings from family members are failing to stem the tide.
The Mechanics of Modern Fraud: Generative AI and Voice Cloning
The baseline capability of fraudsters has shifted dramatically over the past eighteen months. Historically, executing a successful scam required scale; criminals sent millions of poorly translated emails hoping a tiny fraction of recipients would take the bait. Generative artificial intelligence has inverted this economic model, allowing bad actors to optimize for precision rather than volume.
Modern phishing communications—ranging from text messages concerning missed package deliveries to urgent voicemails purportedly from financial institutions—are syntactically flawless, contextually appropriate, and psychologically acute. Furthermore, the advent of accessible voice-cloning software has enabled criminals to orchestrate sophisticated impersonation schemes with minimal raw audio.
Federal law enforcement agencies have repeatedly cautioned the public regarding this capability. The Federal Bureau of Investigation (FBI) has issued specific alerts warning that AI-generated audio and video assets are now frequently indistinguishable from genuine communications. In these scenarios, criminals aggregate publicly available social media data—such as a grandchild’s voice from a graduation video or a family vacation clip—and synthesize an entirely fabricated audio stream.
As Kathy Stokes, director of fraud prevention programs at AARP, has noted, combining the rich personal information available online with authentic voice replication creates an industrial-scale advantage for criminal syndicates. When an aging parent receives a panicked phone call from an entity sounding precisely like their grandchild, claiming to be in an accident and demanding immediate wire transfers without parental notification, the psychological pressure bypasses logical scrutiny.
The Escalating Economic and Social Toll on Older Adults
Older adults remain prime targets for malicious actors due to a convergence of financial stability and generational trust models. Demographically, individuals aged sixty and older are significantly more likely to possess accumulated retirement assets, equity-rich real estate holdings, and established credit histories. Concurrently, this cohort was socialized in an era where institutional authorities—such as banks, tax agencies, and healthcare providers—could be reliably verified through standard communication channels.
Criminals exploit this foundational trust by masquerading as trusted institutions or distressed family members. According to comprehensive data compiled in the FBI’s Elder Fraud Report, older Americans reported staggering financial losses exceeding $3.4 billion in a single recent reporting year, representing an 11 percent increase in direct monetary losses and a 14 percent surge in formal complaints compared to the preceding period.
Criminologists and consumer advocates emphasize that these figures represent a fraction of the actual economic damage. A profound underreporting bias persists within elder fraud statistics. Many victims experience acute psychological distress, feelings of shame, or fear of losing their financial autonomy, leading them to conceal losses from family members and authorities alike. Frequently, the breach only surfaces when a secondary caregiver reviews financial statements or intervenes in daily administrative tasks.
The Inefficacy of Traditional Warning Strategies
For years, the standard societal response to rising fraud rates has been educational paternalism. Caregivers typically address the threat by issuing verbal warnings, distributing informational pamphlets, or forwarding news articles detailing emerging scam vectors. While well-intentioned, empirical data from cybersecurity and behavioral research indicates that static warnings provide negligible long-term protection against sophisticated social engineering.
Human psychology dictates that fear-based warnings, divorced from practical application, do little to build operational resilience. When an individual is confronted with a high-pressure, emotionally charged scenario, theoretical advice is rapidly overridden by acute stress responses.
Conversely, extensive organizational research in digital security demonstrates that resilience against phishing requires experiential learning. Studies conducted within enterprise environments reveal that employees who engage in regular, simulated phishing exercises—identifying and evaluating fake communications in a controlled setting—reduce their susceptibility to real-world phishing attacks by up to 86 percent. Recognition of digital deception functions as a cognitive skill; it is reinforced through active practice and deteriorates without routine application.
Historically, corporate workforces benefited from mandatory, systematic cybersecurity training modules, while retirees—who face the most aggressive financial targeting—were left to navigate the digital landscape with minimal institutional support.
Bridging the Gap Through Practical, Family-Centered Training
Recognizing the mismatch between corporate security standards and consumer resources, private sector innovators and elder advocates have begun adapting enterprise-grade training methodologies for residential use. Platforms such as PhishTested.com have emerged to translate the simulation-based model into accessible formats specifically tailored for households, prioritizing usability for adults aged fifty and above.
Rather than relying on abstract lectures, these platforms utilize interactive scenario libraries. Participants evaluate realistic simulations spanning multiple threat categories—including fraudulent Medicare enrollment notices, compromised banking alerts, and romance scams soliciting gift cards. By deciding whether to trust, verify, or dismiss specific communications, users receive immediate, contextual feedback explaining the underlying indicators of fraud.
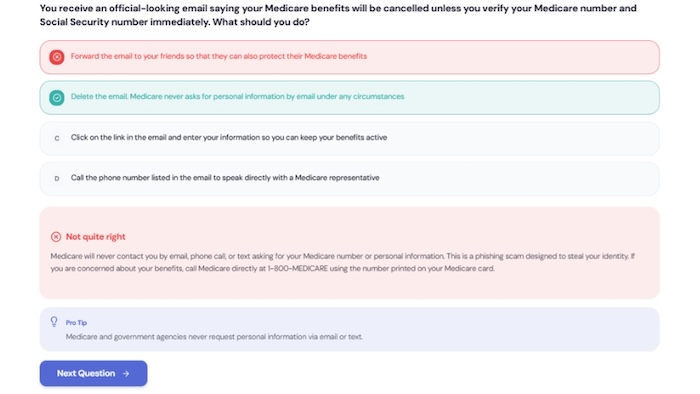
This approach aligns with modern pedagogical insights: short, consistent intervals of practical exposure build intuitive pattern recognition. Furthermore, modern platform architecture often integrates family dashboards, allowing geographically dispersed caregivers to monitor preparedness metrics and coordinate defensive measures without undermining the independence of aging relatives.
Actionable Safeguards for Caregivers and Families
While structured training platforms provide a valuable layer of defense, cybersecurity professionals recommend that families implement foundational operational habits to mitigate risk proactively:
- Establish Multi-Generational Verification Protocols: Families should agree upon a predetermined verbal password or a multi-step verification process for any unusual requests involving financial transfers or urgent assistance, regardless of how authentic the caller’s voice or Caller ID appears.
- Limit Digital Footprint Exposure: Caregivers should assist older relatives in auditing their social media privacy settings, minimizing the public availability of voice samples, family trees, and biographical details that generative AI tools utilize to personalize attacks.
- Centralize Trusted Contacts: Maintain a physical or securely stored digital list of verified contact numbers for financial institutions, healthcare providers, and family members. When an unexpected communication arrives, users must be trained to initiate contact strictly through these pre-determined, verified channels rather than returning incoming calls or clicking embedded links.
Broader Implications and Future Outlook
The persistence of elder fraud poses a systemic challenge to regulatory bodies, financial institutions, and technology providers. As generative models continue to advance, distinguishing between legitimate digital interactions and synthetic fraud will become increasingly complex for all demographic groups.
However, the disproportionate impact on older adults necessitates specialized, proactive interventions that move beyond passive awareness campaigns. By shifting toward active, experiential education and establishing robust family-level communication protocols, caregivers can help bridge the resilience gap. Equipping older adults with the tools to recognize evolving digital threats not only safeguards their accumulated life savings but also preserves their dignity and autonomy in an increasingly digitized world.
Related posts: