Historic Medicare Part D Reforms Take Full Effect in 2026, Capping Out-of-Pocket Drug Costs at $2,100 Annually

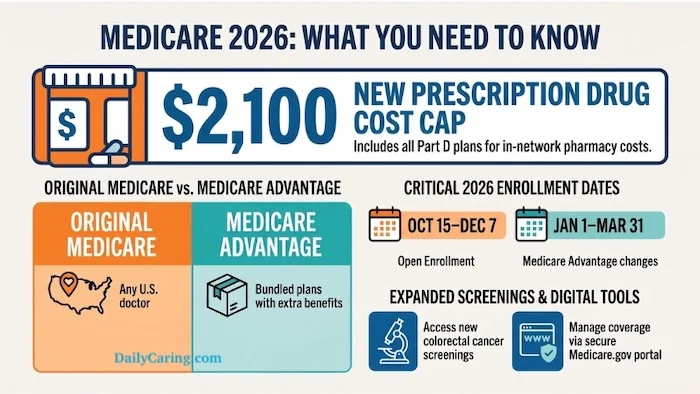
The landscape of prescription drug coverage for millions of American seniors and individuals with disabilities underwent a monumental transformation as of July 1, 2026, with the full implementation of key provisions from the Inflation Reduction Act (IRA). These changes fundamentally restructure Medicare Part D, aiming to alleviate the persistent financial burden associated with managing older adults’ medications. Foremost among these reforms is the establishment of a strict annual cap on out-of-pocket prescription drug costs at $2,100, coupled with the complete elimination of the long-dreaded "donut hole" coverage gap. This shift ushers in an era of unprecedented financial predictability for beneficiaries and their caregivers, marking a significant departure from the convoluted and often financially crippling coverage phases of the past.
The Genesis of Reform: The Inflation Reduction Act
The sweeping changes to Medicare Part D are a direct result of the Inflation Reduction Act of 2022, a landmark piece of legislation signed into law in August 2022. While the IRA encompassed a broad array of provisions addressing climate change, healthcare costs, and tax policy, its impact on prescription drug affordability for Medicare beneficiaries stands out as particularly transformative. The Act’s healthcare provisions were designed to empower Medicare to negotiate drug prices, reduce consumer costs, and stabilize premiums, rolling out in phases over several years.
Prior to the IRA, Medicare Part D, established in 2006, featured a complex benefit design with multiple phases: a deductible, an initial coverage phase, a coverage gap (the "donut hole"), and a catastrophic phase. This structure often led to significant financial instability for beneficiaries, particularly those with chronic conditions requiring expensive medications. The "donut hole," in particular, was a source of immense stress, forcing seniors to pay a substantial percentage of their drug costs after initial coverage limits were met but before catastrophic coverage kicked in. The IRA aimed to simplify this structure and provide tangible relief.
The journey to the 2026 reforms began with earlier provisions, such as capping insulin costs at $35 per month for Medicare beneficiaries starting in 2023 and making recommended vaccines free. The current year, 2026, represents the culmination of these efforts, fundamentally redesigning the Part D benefit to provide greater financial security.
The Demise of the "Donut Hole": A Decade of Financial Strain Ends
For over a decade, the "donut hole," officially known as the coverage gap, was arguably the most financially destructive element of Medicare Part D for seniors. This phase was triggered when a beneficiary and their plan had spent a combined amount on covered drugs (the initial coverage limit). Once in the donut hole, beneficiaries were suddenly responsible for a significantly higher percentage of their drug costs – often 25% for both generic and brand-name drugs – until their out-of-pocket spending reached a specific threshold, at which point catastrophic coverage would begin.
This unpredictable cost spike often forced seniors to make difficult choices between essential medications and other necessities, or to ration their prescriptions, leading to adverse health outcomes. Caregivers, too, faced immense challenges in budgeting for these fluctuating and often exorbitant drug expenses. For many, the donut hole represented a period of severe financial anxiety.
As of 2026, this infamous coverage gap has been permanently eliminated. The IRA’s redesign of Part D ensures that beneficiaries will no longer experience this intermediate phase of increased cost-sharing. Instead, they will transition directly from the initial coverage phase to the catastrophic phase once their annual out-of-pocket spending reaches the new $2,100 cap. This streamlined benefit structure simplifies budgeting and provides a clear ceiling for medication expenses, a welcome change for millions.
Understanding the New Cost Structure: Caps and Deductibles
The 2026 Medicare Part D changes introduce a simplified and significantly more predictable cost-sharing model. Two primary figures define this new landscape:
-
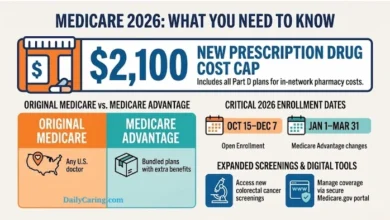
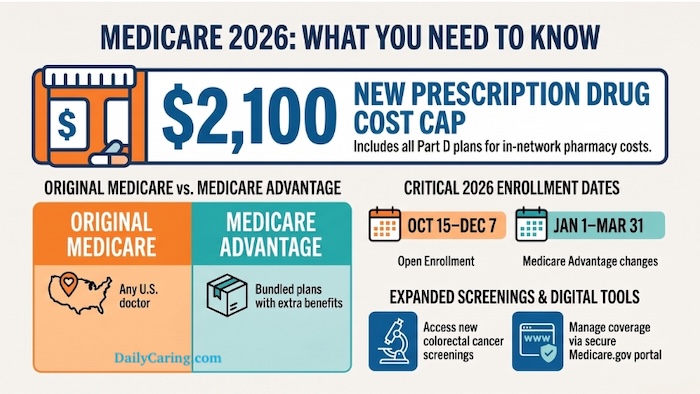
Annual Out-of-Pocket Cap: $2,100
This is the cornerstone of the 2026 reforms. Once an enrollee’s total out-of-pocket spending for covered prescription drugs reaches $2,100 within a single calendar year, their Medicare Part D plan or Medicare Advantage plan (which often includes Part D benefits) will cover 100% of the cost of all subsequent covered medications for the remainder of that year. This means beneficiaries will pay nothing for their covered drugs once this threshold is met. This eliminates the previous 5% coinsurance requirement in the catastrophic phase, providing complete financial relief for those with high drug costs. -
Standard Deductible: $615
For 2026, the maximum standard deductible for Medicare Part D plans is legally set at $615. This is the amount a beneficiary must pay out of pocket for covered prescriptions before their plan begins to pay its share. While plans can offer lower deductibles, they cannot exceed this statutory maximum. It is crucial for beneficiaries to understand that this deductible contributes towards the $2,100 out-of-pocket cap.
To illustrate, consider a beneficiary with high medication costs. After meeting their $615 deductible, they would continue to pay their copayments and coinsurance during the initial coverage phase. All these payments accumulate towards the $2,100 out-of-pocket maximum. Once that $2,100 mark is hit, their financial responsibility for covered drugs drops to zero for the rest of the year. This clarity and predictability offer substantial peace of mind and tangible financial relief, particularly for the estimated 1.5 million Medicare beneficiaries who previously spent more than $2,000 annually on prescription drugs.
Empowering Beneficiaries: The Medicare Prescription Payment Plan
Recognizing that even a $615 deductible or accumulated copays could present a significant upfront financial challenge, especially at the beginning of the year, the 2026 mandates also include the continuation and enhancement of the Medicare Prescription Payment Plan. This innovative program is designed to smooth out-of-pocket costs over the entire calendar year, preventing beneficiaries from facing large, immediate bills at the pharmacy counter.
The Medicare Prescription Payment Plan is an opt-in program, meaning beneficiaries must actively choose to enroll. Once enrolled, instead of paying their deductible and subsequent cost-sharing amounts in lump sums as they fill prescriptions, their out-of-pocket costs (up to the $2,100 cap) are spread evenly across monthly payments. The pharmacy bills the insurance plan, and the insurance plan then sends the enrollee a manageable monthly bill. This initiative is particularly beneficial for those on fixed incomes or managing tight budgets, transforming unpredictable drug expenses into predictable monthly installments. It provides a vital budgeting tool for seniors and their caregivers, making access to necessary medications more financially feasible throughout the year.
Navigating the Nuances: Formulary Manipulation and the Call for Vigilance
While the new out-of-pocket cap and the elimination of the donut hole offer significant financial relief, beneficiaries and their caregivers must remain highly vigilant. Insurance companies are not absorbing these new costs out of altruism; they are actively seeking ways to mitigate the financial impact of these mandated caps on their own bottom lines. One of the most significant threats to beneficiaries’ access to affordable medications is formulary manipulation.
Formularies are the lists of prescription drugs covered by a particular plan. Insurance providers are aggressively reviewing and adjusting these lists, often shifting medications into higher pricing tiers or, in some cases, dropping coverage for certain drugs entirely. A medication that was fully covered and affordable in 2025 may become significantly more expensive or even uncovered in 2026. This practice directly impacts beneficiaries because only spending on drugs explicitly listed on a plan’s formulary counts toward the $2,100 out-of-pocket cap. If a drug is not on the formulary, the money spent on it does not contribute to reaching the maximum, leaving beneficiaries to pay the full cost out of pocket, on top of their capped expenses for covered drugs.
This makes the Annual Enrollment Period (AEP), typically from October 15 to December 7 each year, absolutely critical. During this window, beneficiaries and their caregivers must meticulously verify that all of their loved one’s specific medications remain on their chosen plan’s formulary for the upcoming year. Failure to do so could lead to unexpected high costs or the need to switch medications, which can be medically complex and disruptive. Tools available on Medicare.gov allow for direct comparison of plans and their formularies, making this verification process manageable but mandatory.
Premium Stabilization: A Guardrail Against Soaring Monthly Costs
Another crucial, though less publicized, Medicare Part D change included in the Inflation Reduction Act is the premium stabilization program. This provision aims to prevent insurance companies from simply offsetting the new out-of-pocket caps by drastically increasing monthly premiums. The law caps base premium increases for Part D plans at 6% per year. This measure is intended to provide a degree of stability to the monthly costs beneficiaries pay for their drug coverage.
However, it is vital to understand that this 6% cap applies to the "base premium" – a standardized amount calculated across all Part D plans. Individual plan premiums can still fluctuate based on a variety of factors, including the specific benefits offered, the plan’s cost management strategies, and its geographic service area. Therefore, while the premium stabilization program offers a protective measure against runaway increases, it does not eliminate the need for diligent annual comparison shopping. Beneficiaries should still review their coverage options during the Annual Enrollment Period to ensure they are enrolled in the most cost-effective plan that covers their specific medications, balancing monthly premiums with potential out-of-pocket costs.
Broader Impact and Stakeholder Reactions
The 2026 Medicare Part D reforms represent a significant shift with wide-ranging implications for various stakeholders:
- For Seniors and Caregivers: The most direct and positive impact is the substantial financial relief and increased predictability. The $2,100 cap means that even those with the highest drug costs can now budget with certainty, alleviating a major source of stress. The Prescription Payment Plan further enhances this by spreading costs. This allows for better overall financial planning for eldercare, freeing up resources that might otherwise have been consumed by unpredictable drug expenses.
- For Pharmaceutical Companies: The IRA’s provisions, including the out-of-pocket cap and future drug price negotiation, place significant pressure on pharmaceutical companies. While they maintain that these measures could stifle innovation and R&D, the reality is that they are being compelled to reconsider their pricing strategies and engage in more competitive practices.
- For Insurance Providers: Medicare Part D plans are being forced to adapt their business models. While the premium stabilization cap offers some protection, the elimination of the catastrophic reinsurance phase (where Medicare previously covered 80% of costs) and the new out-of-pocket cap mean insurers now bear a greater share of the financial risk for high-cost beneficiaries. This explains the aggressive formulary management and the strategic redesign of plan offerings. Insurers will likely focus on negotiating lower drug prices with manufacturers and implementing robust utilization management programs.
- Advocacy Groups: Organizations representing seniors and patient advocates have largely hailed these reforms as a historic victory. Groups like AARP have long campaigned for measures to lower prescription drug costs and eliminate the donut hole, seeing the IRA’s provisions as a major step towards making healthcare more affordable and accessible for older Americans.
- Government: The Biden administration has frequently highlighted the IRA’s drug pricing provisions as a key achievement, demonstrating a commitment to lowering healthcare costs for consumers. These reforms are positioned as a crucial component of broader efforts to strengthen Medicare and ensure its long-term sustainability.
A Look Ahead: Continuous Evolution of Drug Pricing Policy
The 2026 changes are not the final word on Medicare Part D or drug pricing in the U.S. The Inflation Reduction Act also introduced provisions for Medicare to directly negotiate the prices of certain high-cost prescription drugs, a program that began with a limited number of drugs in 2024 and will expand in subsequent years. This ongoing negotiation process, coupled with potential future legislative actions, suggests a continuous evolution in how prescription drugs are priced and covered for Medicare beneficiaries. The current reforms lay a foundational framework for greater affordability and predictability, but stakeholders must remain informed and adaptable as the policy landscape continues to shift.
Practical Steps for Beneficiaries and Caregivers in 2026
Given the significant changes, proactive engagement is paramount:
- Review Your Plan Annually: During the Annual Enrollment Period (AEP), meticulously compare your current Part D plan with other available options. Pay close attention to formularies to ensure all necessary medications are covered.
- Utilize Official Resources: The official Medicare Part D portal at Medicare.gov/health-drug-plans is an invaluable tool for comparing plans, checking formularies, and learning more about the Medicare Prescription Payment Plan.
- Consult Experts: If the choices seem overwhelming, seek guidance from a qualified Medicare advisor, a financial planner specializing in eldercare, or a local State Health Insurance Assistance Program (SHIP).
- Consider the Prescription Payment Plan: If managing upfront costs is a concern, investigate enrolling in the opt-in Medicare Prescription Payment Plan to spread out your out-of-pocket expenses.
The 2026 Medicare Part D reforms represent a landmark achievement in prescription drug affordability, offering millions of seniors and their caregivers a significant reprieve from the financial strain of high medication costs. The elimination of the donut hole and the implementation of a clear out-of-pocket cap provide unprecedented financial predictability. However, the onus remains on beneficiaries and their advocates to stay informed and actively manage their coverage to fully leverage these benefits and navigate the evolving strategies of insurance providers.
| Medicare Policy Area | 2026 Update Details **
Author: Chris Clark
Edited by: Amie Clark, BSW
Updated on: July 1, 2026
Managing an older adult’s medications has historically been a persistent financial drain, often leading to unpredictability and stress for caregivers and beneficiaries alike. Navigating the convoluted coverage phases of Medicare Part D made budgeting a Herculean task. However, with the final implementation phases of the Inflation Reduction Act taking full effect in 2026, significant reforms are now in place, fundamentally reshaping the prescription drug market for Medicare beneficiaries and bringing much-needed financial predictability.
Thanks to this landmark legislation, out-of-pocket costs for covered prescription drugs are now strictly capped at $2,100 annually. This represents a monumental
Related posts: